Accounting and finance
Monthly management accounts and cash reporting
See how the business performed, why the figures moved and what needs attention. Andrew prepares management accounts from your records, with commentary and follow-up actions.
Checking the records first
Before preparing the report, we check the reconciliations and list missing information. Estimates and figures awaiting review are labelled.
The detail depends on how you use the accounts. Some businesses need a short monthly pack; others need results by department, project or sales channel. We agree the level of detail and the records behind it.
What the report can include
Reports use consistent periods and comparisons. Commentary explains significant movements and open questions, with supporting schedules behind them.
- Profit and loss and balance sheet.
- Comparisons with prior periods or an agreed budget.
- Cash balances, customer amounts due and supplier commitments.
- A management action list with questions, decisions and follow-up responsibilities.
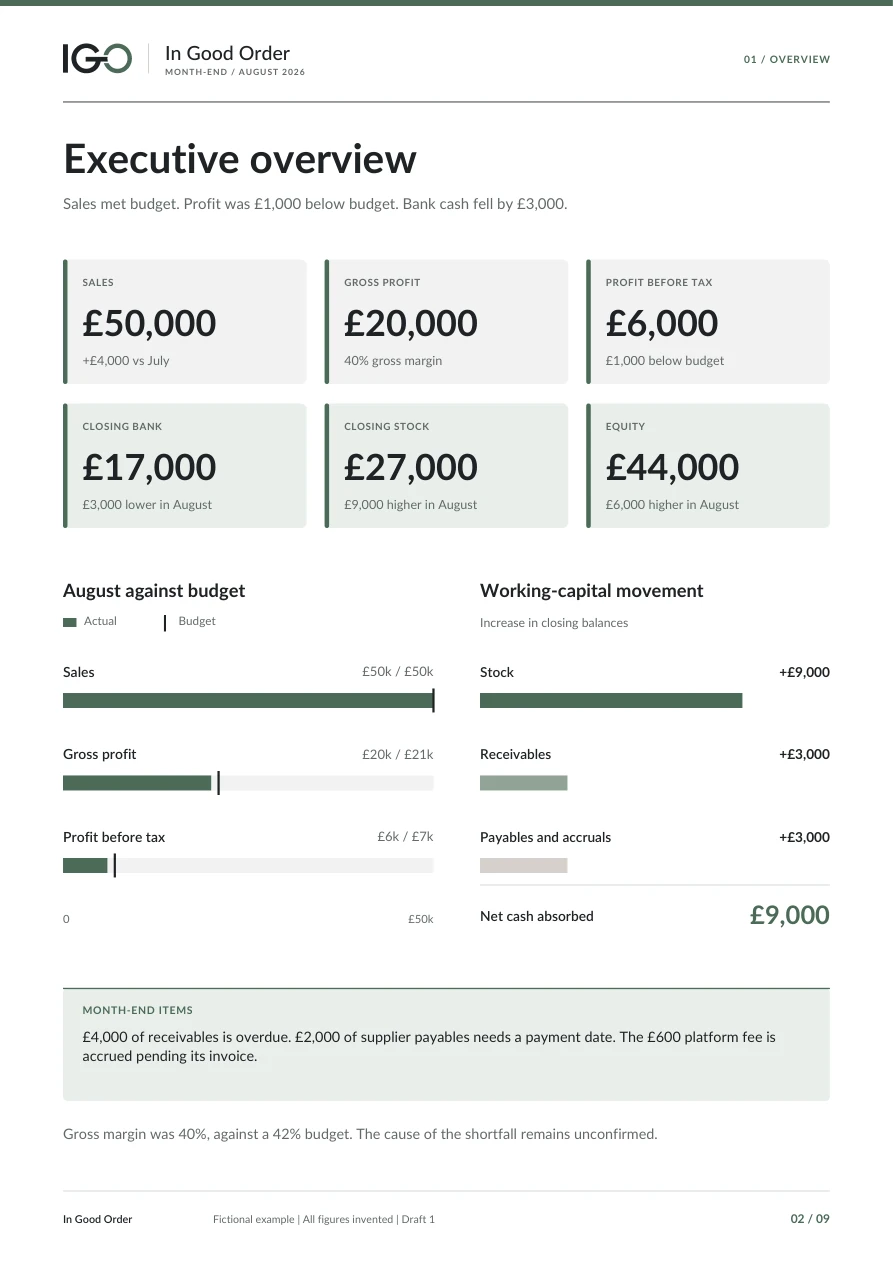 Executive overview · page 2 of 9
Fictional example · August 2026
Example management pack
This example shows a profitable month in which bank cash fell. It explains the movement and records what still needs checking.
- Sales and profit compared with the previous month and budget.
- The gross-margin shortfall, whose cause is still unconfirmed.
- How changes in stock and unpaid balances explain the movement from profit to cash.
- Outstanding items with a responsible role and next step.
PDF · 9 pages · 149 kB. All figures are invented.
Explore the example onlineReporting scope and additional work
We agree the reporting basis and who reviews adjustments, and work with your existing accountant if you have one. Fees reflect the state of the records, the reporting detail and the review work. Building opening schedules or recovering historical information is quoted separately.
The price list has two reporting additions: the month-end close with Xero’s standard reports, and a short written monthly report. Management accounts with fuller commentary, like the example pack, are quoted for the detail you need.
A cash forecast can be added. It uses assumptions agreed with you, keeps expected receipts and planned spending apart from recorded transactions, and shows when assumptions change.
Questions about this support
Do we need monthly management accounts?
Not always. It depends on how you use the figures and how fast the business changes. We talk through the decisions you need to make, then recommend how often to report.
Can you report from bookkeeping done elsewhere?
Yes, after a handover and review of the records. Any gaps that affect the report are listed, with who will resolve each one.
Discuss your accounts
Contact Andrew about the accounting work you need.
Opens a short enquiry form. Nothing is sent until you press Send enquiry.
Prefer email? Write to andrew@ingoodorder.co.uk.
Know a business that would benefit? Introduce them and I’ll pay you £50 when they sign up.